A hailstorm can leave a roof looking perfectly normal from the driveway while creating damage that shortens shingle life, exposes weak points, and leads to leaks months later. A hail damage roof insurance claim is easier to manage when you act early, document what happened, and have a qualified local roofer inspect the full roofing system before small issues turn into expensive interior repairs.
For North Texas property owners, timing matters. Hail, high wind, and driving rain often arrive together, and another storm can worsen an already damaged roof. The goal is not to rush into a replacement decision. It is to get clear facts, protect the property, and give your insurance carrier the documentation needed to evaluate the loss.
Start Your Hail Damage Roof Insurance Claim With an Inspection
After a storm, do not climb onto the roof yourself. Wet surfaces, loose granules, damaged shingles, and hidden soft spots make that risky. Start by checking safely from the ground for visible signs such as shingles in the yard, dented metal vents, damaged gutters, torn window screens, or impacts on fencing and outdoor equipment.
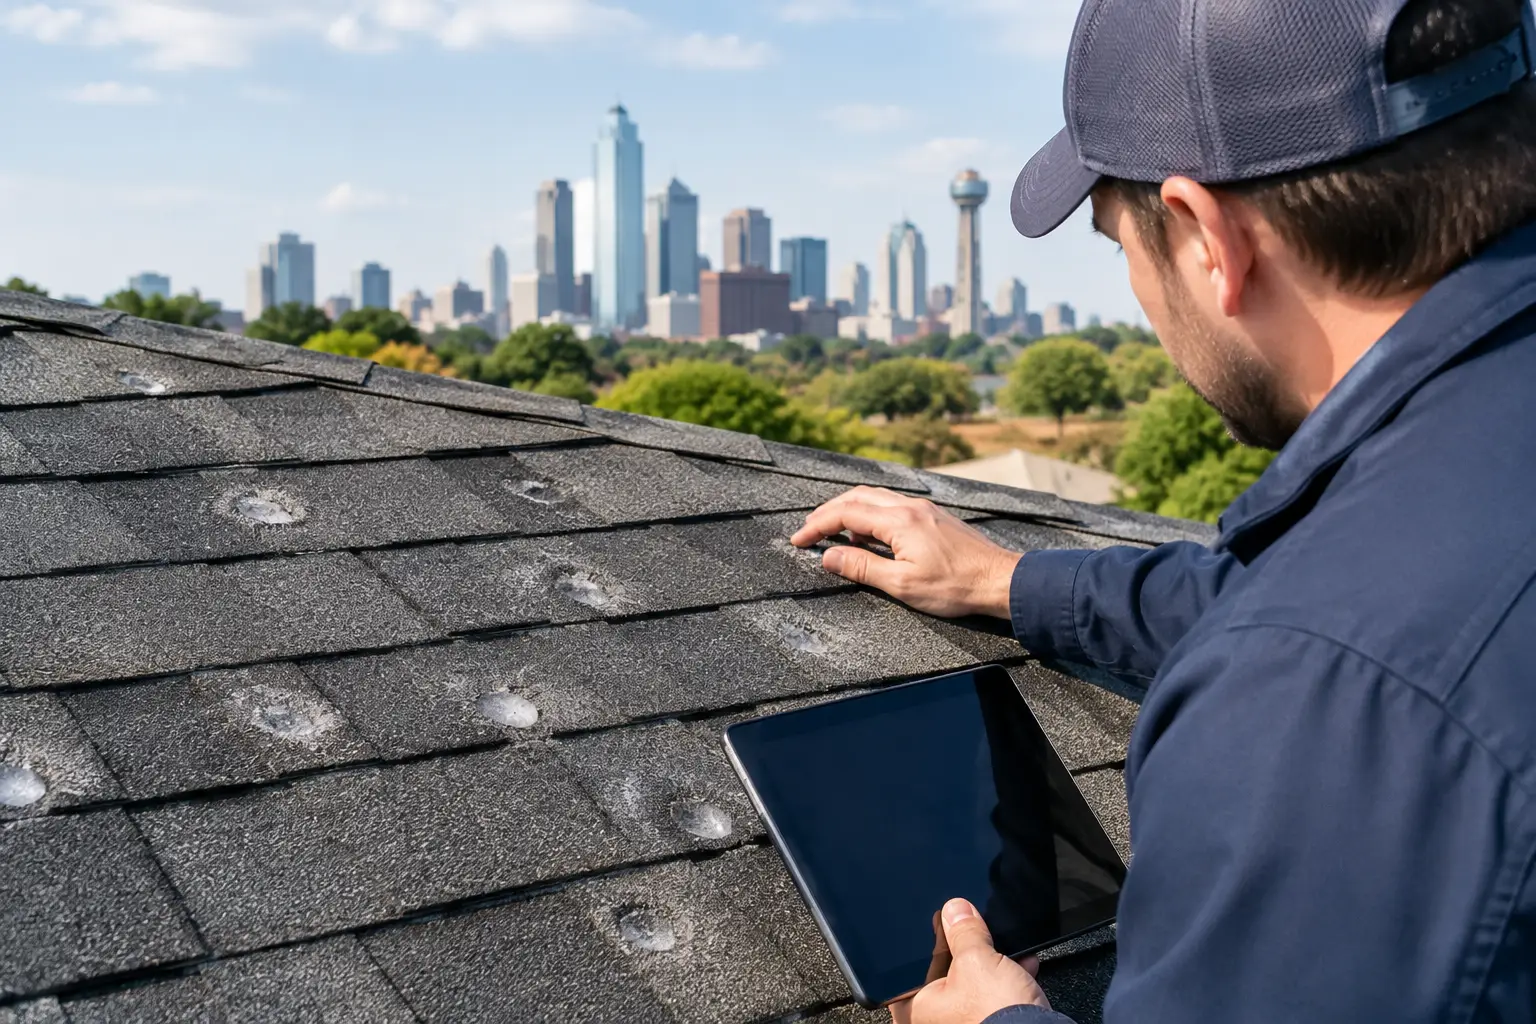
Those signs do not automatically prove your roof needs replacement, but they can support the case for a professional inspection. Hail damage may appear as bruising, fractured shingle matting, granule loss, cracked tabs, or impact marks on roof accessories. On commercial roofs, damage can look different depending on whether the system is TPO, PVC, modified bitumen, metal, or another material.
A thorough inspection should look beyond the shingles. Flashing, pipe boots, ridge vents, skylights, gutters, downspouts, and roof penetrations all deserve attention. If the roof has damage but the gutter system does not drain correctly, water can still create problems around the eaves, siding, foundation, or entryways.
At Reilly Roofing and Gutters, the first step is a no-cost, no-obligation inspection that gives property owners a straightforward assessment of the roof's condition. If repairs are appropriate, that should be clear. If the storm damage supports an insurance claim or replacement, the documentation should explain why.
Document the Damage Before Filing
Insurance claims are built on details. Take photographs and short videos from safe locations as soon as conditions allow. Capture the date of the storm if possible, the overall property, and close-ups of visible damage to gutters, vents, screens, siding, fencing, and other exterior components.
Keep a simple written record as well. Note when the storm occurred, when you first noticed the damage, any leaks or water stains, and temporary steps taken to prevent additional damage. Save receipts for emergency mitigation, such as a tarp installation or water removal. Your policy generally requires you to take reasonable steps to prevent further damage, but avoid permanent repairs before the carrier has had a chance to inspect unless they are necessary to keep the property safe.
It also helps to locate your current insurance policy and review the declarations page. Look for your deductible, roof settlement terms, and any endorsements that may affect payment. Some policies pay replacement cost value, while others may account for depreciation or provide actual cash value coverage. The difference can be significant, especially for an older roof.
A roofing contractor cannot interpret your policy or promise what an insurer will approve. What a contractor can do is identify storm-related damage, provide repair or replacement information, and help you understand the scope of work being discussed.
File Promptly, but Do Not Guess at the Scope
Once an inspection confirms likely hail or wind damage, contact your insurance carrier to begin the claim. Most carriers allow claims by phone, online portal, or mobile app. Provide accurate basics: the date of loss, your property address, visible damage, and any urgent repairs already completed.
Do not feel pressured to estimate the entire cost yourself. That is what the inspection, adjuster visit, and contractor documentation are for. Guessing at damages can create confusion later. Be factual, keep copies of every communication, and write down claim numbers, adjuster names, and appointment dates.
Many homeowners worry that filing a claim guarantees a premium increase or that a claim must be filed only after a contractor says the roof needs full replacement. Neither assumption is always true. Premiums and eligibility are determined by the insurer, policy history, regional losses, and other factors. Likewise, some storm-damaged roofs can be repaired, while others have widespread damage that makes replacement the more practical option. The right answer depends on the roof system, its age, local code requirements, matching considerations, and the documented extent of the loss.
Be Present for the Adjuster Inspection
Your carrier will assign an adjuster to inspect the property or review the claim. When possible, ask your roofing contractor to be present at that appointment. This is not about arguing with the adjuster. It is about making sure storm-related conditions are easy to locate, safely access, and accurately documented.
A contractor can point out test areas, damaged components, code-related considerations, and the condition of the full system. That includes items an adjuster may not see from one roof slope, such as soft metal damage, compromised flashing, or hail impacts on accessories. For commercial properties, the inspection may also involve drainage details, seams, rooftop equipment, and membrane conditions.
After the visit, review the insurer's estimate carefully. Compare the listed materials, measurements, labor items, waste factors, accessories, and code allowances with the actual scope required to restore the property. If something appears missing, your contractor can provide supporting documentation and request that the carrier review the item. This is commonly called a supplement process.
A supplement is not automatically a dispute. It is often part of completing a claim correctly when hidden damage, code requirements, or necessary roofing components were not included in the first estimate.
Understand Deductibles, Depreciation, and Payment Timing
Your deductible is the portion of a covered loss you are responsible for paying. In Texas, a legitimate contractor should not offer to waive, absorb, or disguise that deductible. Be cautious of any storm chaser who makes that promise, pushes you to sign immediately, or asks you to sign over insurance benefits without a clear explanation.
Insurance payments may arrive in stages. An initial payment can reflect actual cash value, with recoverable depreciation released after the approved work is completed and proper documentation is submitted. Your policy controls the process, so ask your carrier questions about deadlines, depreciation, and required paperwork.
Before construction begins, make sure you understand the contractor's written scope, materials, warranty options, project schedule, payment terms, and cleanup plan. A reputable roofing company should be able to explain whether the work includes underlayment, ice and water protection where required, flashing, ventilation, ridge components, gutters, and disposal. A low estimate that leaves out necessary details can become costly later.
Choose a Local Contractor Who Will Still Be Here
After a major DFW hailstorm, out-of-state crews often arrive quickly. Some may do quality work, but property owners should take time to verify local presence, insurance, licensing requirements where applicable, manufacturer credentials, references, and warranty terms.
The lowest bid is not always the best value. Roofing is a system, not just a layer of shingles. Proper installation, ventilation, flashing, underlayment, and drainage all affect how the roof performs through future Texas heat, wind, and hail.
For qualifying systems, manufacturer-certified installation and strong warranty coverage can add meaningful protection. Ask what is covered, how long it lasts, whether workmanship is included, and who will handle service if a problem develops after the job is complete.
What if the Claim Is Denied or Underpaid?
A denial does not always mean the end of the conversation. First, request and review the carrier's explanation. The reason may be that the damage was considered wear and tear, prior damage, cosmetic-only damage, excluded material damage, or below the deductible. In other cases, the estimate may recognize some storm damage but omit necessary line items.
A qualified roofer can provide photographs, inspection findings, measurements, and a detailed scope for your records. If new information supports reconsideration, submit it through the carrier's established process. Stay professional, keep everything in writing, and meet any deadlines in your policy.
The best next step after hail is simple: protect the property, get a knowledgeable inspection, and make decisions based on documented conditions rather than pressure or guesswork. That approach gives your roof, your claim, and your peace of mind a much stronger foundation.